Key Takeaways
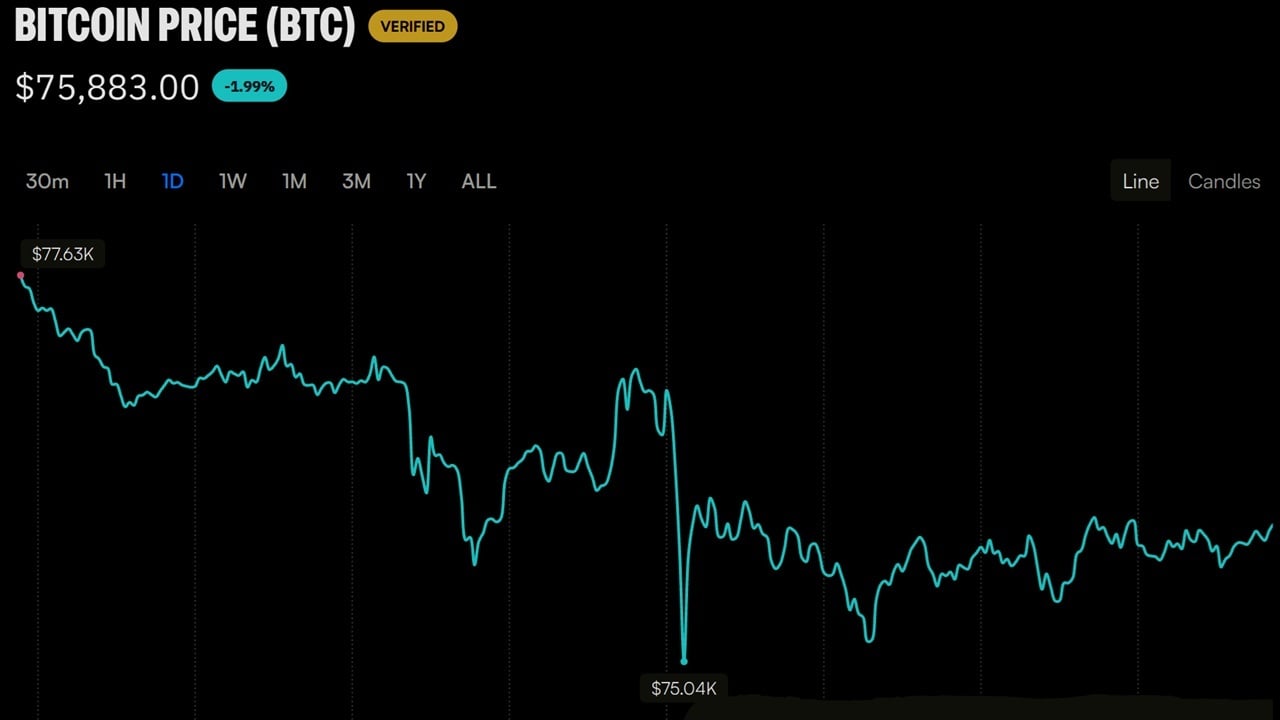
- Charles Edwards set $78,000 as the weekly close bitcoin must reclaim, with BTC near $75,850 on Sept. 16.
- Popular analyst Credible Crypto has told his followers that BTC’s bottom is within 10% of current levels before a potential 200%-plus rally.
- Bitcoin broke under $75,000 for the first time since Aug. 20 as $771.82 million in positions were liquidated.
One Level, One Deadline
Edwards did not mince his words in terms of bitcoin’s near-term trajectory earlier today, stating:
Bitcoin needs a weekly close back above $78K pronto or this could get ugly.
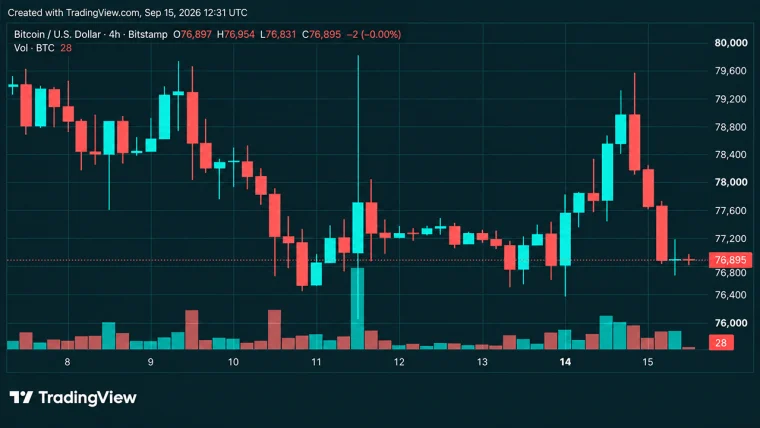
He also attached a chart to showcase his firm’s bearish outlook, adding that the number chosen was not arbitrary. Edwards pointed out that bitcoin’s price has spent September trapped under a contained range running from roughly $77,100 to $78,400, and the $79,000 area has rejected every attempt to break out of it.
Reclaiming $78,000 on a weekly basis could be the first evidence the band has flipped.
At press time, bitcoin is trading near $75,900, down 2% over 24 hours. That leaves the reclaim roughly 2.8% away, with the weekly candle already deep into the red.
Capriole’s outlook puts major incoming resistance at around $93,500, a level Edwards has said would need a weekly close to open a run toward six figures. Until then, his read is one with a bearish bias with a 12-to-18-month window shaped by long-term holder selling.
That said, not every analyst reading these data points is seeing red. Popular pundit Credible Crypto, who has over 480,000 followers on X, told investors:
Bottom on BTC is somewhere between where we are now and about 10% lower before a 200+% rally to the upside.
Ten percent lower is roughly $68,300, while a 200% rally from there clears $200,000.
What’s Causing All the Ongoing Turmoil
The catalyst for the ongoing bloodbath hasn’t been technical, but the U.S. Senate blocking the CLARITY Act on a 49-50 cloture vote on Sept. 15, falling 11 votes short of the 60 needed to open debate on crypto market structure.
Bitcoin fell below $75,000 for the first time since Aug. 20 within minutes. Roughly $289 million in leveraged positions were liquidated in the hour around the vote, about 91% of them longs, and the 24-hour total reached $771.82 million across more than 120,000 traders.
Exchange-traded fund (ETF) flows told the same story, with bitcoin ETFs shedding $450.4 million on the day, with Blackrock’s IBIT losing $161.7 million and Fidelity’s FBTC losing $214.8 million.
Bitcoin.com News reported ahead of the vote that bitcoin’s price was already sitting on support after a brutal $79,000 rejection, with the $76,000 to $76,700 zone described as the line in the sand (one that did not end up holding).
The Week That Decides It
Over the coming few weeks, bitcoin needs to print a weekly close above $78,000, a level below which everything is noise, including the intraday bounces that have repeatedly stalled in the $77,100 to $78,400 band this month.
The upcoming calendar isn’t helping either, given that bitcoin’s price action has a narrow run of macro dates left this month to escape the $80,000 ceiling, and the legislative catalyst bulls were counting on is now dead until at least the lame duck session.
What remains is a market that has lost its policy story and is back to defending levels. Edwards has named the one that matters, and traders get their answer at the weekly close.