Key Takeaways
- Kalshi’s 15-minute gold markets traded 539 million contracts in September, against 317 million for Ether.
- 15-minute markets made 80% of Kalshi’s non-sports fees in the week to Oct. 5, according to InGame.
- Bitcoin still dominates, with 6.74 billion 15-minute contracts traded in September.
Gold Passes Ether in Its Second Month
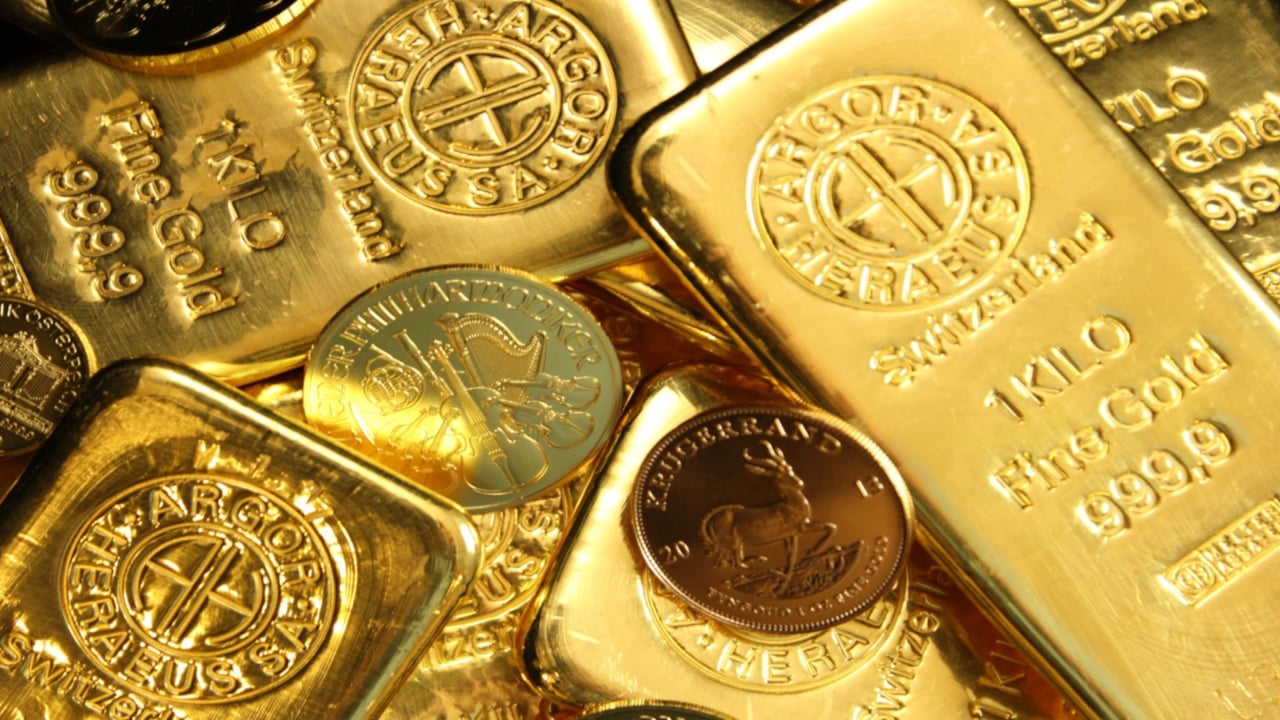
Kalshi’s 15-minute gold markets traded more contracts than its ether markets of the same length in September. According to the exchange’s public market data, 539 million gold contracts changed hands in 15-minute markets that settled during the month, against 317 million for ether.
Cointelegraph reported the shift on Oct. 7, estimating gold’s September fees at about $5 million and ether’s at $2.6 million, based on data from the analytics site Predict Charts.
A Bitcoin.com News estimate based on every September trade and Kalshi’s published fee formula puts gold’s taker fees at $4.94 million, in line with the above figure. That works out to under one cent per contract on average.
Kalshi listed its first 15-minute gold markets on July 31, and trading picked up from August. Gold trailed ether that month—with 213 million contracts against 271 million—then passed it in September despite running about 18% fewer markets, since gold does not trade around the clock. Ether’s own growth had been steep: Kalshi data bears out estimates of 15-minute volume at 6.1 million contracts in January and 233 million in July.
Bitcoin remains far ahead of both. Kalshi’s 15-minute markets traded 6.74 billion contracts in September, and per Predict Charts data, it’s estimated that they brought in $60.4 million in fees. The two crypto series settle on CF Benchmarks prices, while gold settles on a Pyth Network price feed, an onchain oracle. Kalshi said in September that its commodities volume reached $400 million within seven months, more than four times what its crypto markets had done at the same stage.
The gold figures sit inside a product line that has come to dominate Kalshi’s business outside sports. Fifteen-minute crypto, commodity, and financial index markets brought in $20.4 million of Kalshi’s $25.1 million in non-sports fees in the seven days to Oct. 5, according to an InGame analysis, while sports brought in $73.5 million.
Kalshi’s published fee schedule charges takers 0.07 times the number of contracts times the price times one minus the price, so fees peak at 1.75 cents a contract on prices near 50 cents. Estimates like these exclude the rebates Kalshi pays market makers, the same caveat that applied to the $26 million its parlay maker fee raised in its first four weeks.
Speedy Markets Face Criticism
The format has its critics. In June, the gambling industry newsletter Earnings+More wrote that 15-minute crypto contracts announced by Coinbase “echo in-play betting more than investing.”
Abdullah Mahmood, a problem gambling counselor at Ohio treatment center Maryhaven, told NPR that markets expiring “in a matter of minutes or hours are no different than a slot machine in your pocket.” Kalshi spokesperson Dani Lever told NPR the exchange model is healthier than a sportsbook’s because “our profits aren’t tied to trader losses.”
The contracts may stand on firmer legal ground than Kalshi’s sports markets. Courts that ruled against those markets asked whether a contract is tied to a financial consequence, and the Sixth Circuit rejected Kalshi’s sports contracts because game results have only “downstream” economic effects. A contract on the price of gold or bitcoin is tied to the asset’s price itself.
Kalshi’s crypto products have still drawn scrutiny: Last month, the CFTC was reported to be reviewing nearly identical trades in its ether perpetual, which is a separate product from the 15-minute markets.